1-0 Buydown vs. 2-1 Buydown: What’s the Difference?
Temporary mortgage buydowns can help reduce a homebuyer’s payments during the first few years of a loan. Two options buyers may encounter are a 1-0 buydown and a 2-1 buydown.
The main difference is how much payment relief each structure provides and how long that relief lasts.
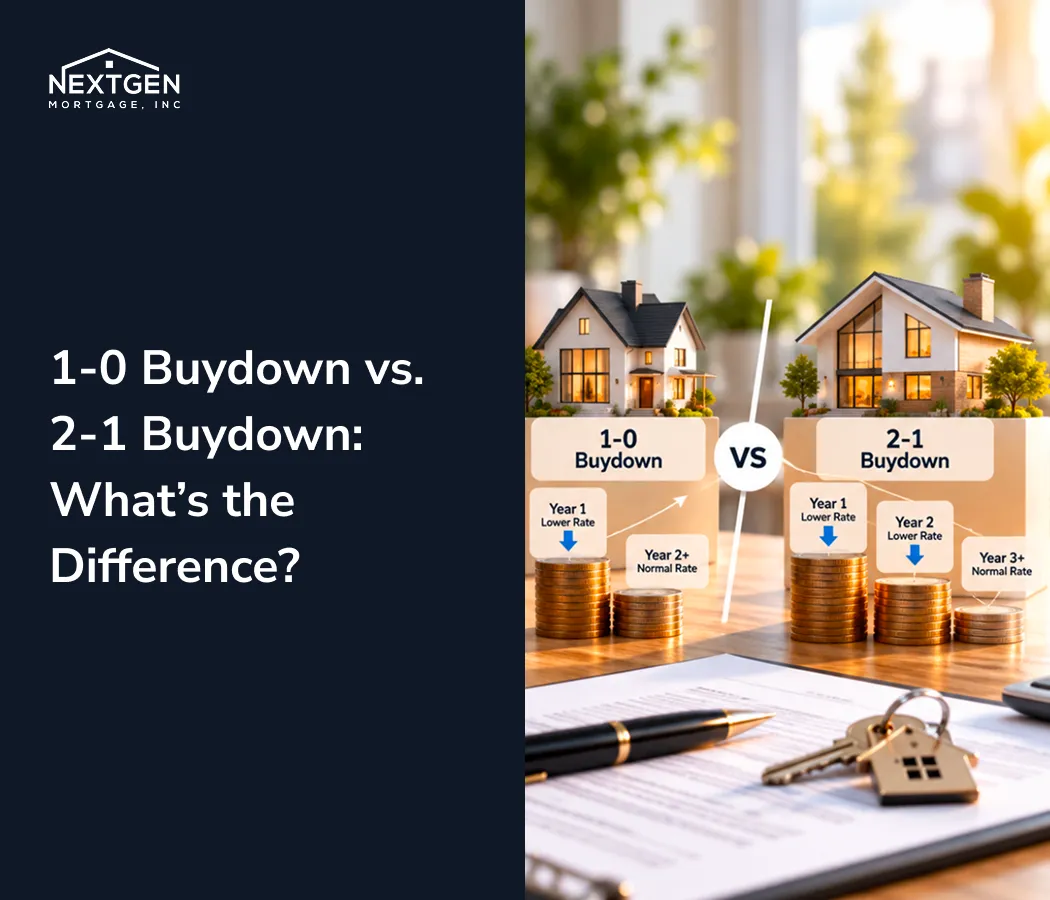
A 1-0 buydown generally reduces the borrower’s payment for the first year by calculating it as though the mortgage rate were 1 percentage point lower. Beginning in Year 2, the borrower makes the full scheduled payment based on the note rate.
A 2-1 buydown provides a larger and longer reduction. The first-year payment is generally calculated as though the rate were 2 percentage points lower, followed by a 1 percentage point reduction in Year 2. The full scheduled payment begins in Year 3.
Because a 2-1 buydown provides a larger subsidy over a longer period, it generally costs more to fund.
Neither option is automatically better. The right choice depends on the loan amount, available seller or builder contribution, how much temporary payment relief the buyer values, and whether the full future mortgage payment is affordable.
1-0 vs. 2-1 Buydown at a Glance
Here is the basic difference between the two structures:
Feature | 1-0 Buydown | 2-1 Buydown |
Temporary subsidy period | 1 year | 2 years |
Year 1 payment basis | Note rate minus 1 percentage point | Note rate minus 2 percentage points |
Year 2 payment basis | Full note-rate payment | Note rate minus 1 percentage point |
Full payment begins | Year 2 | Year 3 |
First-year payment reduction | Smaller | Greater |
Typical funding requirement | Lower | Higher |
Main benefit | Lower-cost short-term relief | Greater and longer temporary relief |
The main difference is simple: a 1-0 buydown provides one year of temporary payment relief and generally requires less money to fund. A 2-1 buydown provides a larger reduction during the first year plus an additional year of payment assistance.
How Does a 1-0 Buydown Work?
A 1-0 buydown temporarily reduces the amount the borrower pays during the first year of the mortgage.
Suppose a homebuyer obtains a mortgage with a 7.00% note rate.
With a 1-0 buydown:
Year 1: payment calculated as though the rate were 6.00%
Year 2 and beyond: full payment based on the 7.00% note rate
The mortgage itself still has a 7.00% note rate.
Temporary buydown funds cover the difference between the reduced Year 1 payment and the full scheduled mortgage payment.
Once the first year ends, the subsidy ends and the borrower begins making the full scheduled payment.
How Long Does a 1-0 Buydown Last?
A 1-0 buydown provides temporary payment assistance for one year.
The borrower typically begins making the full scheduled mortgage payment in Year 2.
That shorter subsidy period is one reason a 1-0 buydown generally costs less than a 2-1 buydown.
How Does a 2-1 Buydown Work?
A 2-1 buydown follows the same basic principle but provides payment assistance for two years.
Using the same 7.00% mortgage rate:
Year 1: payment calculated as though the rate were 5.00%
Year 2: payment calculated as though the rate were 6.00%
Year 3 and beyond: full payment based on the 7.00% note rate
Again, the underlying note rate does not change.
The temporary buydown fund covers part of the scheduled mortgage payment during Years 1 and 2.
For a deeper explanation, read How a 2-1 Buydown Works.
1-0 Buydown vs. 2-1 Buydown Example
Consider a hypothetical homebuyer financing:
Loan amount: $400,000
Loan term: 30 years
Note rate: 7.00%
For simplicity, these examples include principal and interest only. Property taxes, homeowners insurance, mortgage insurance, HOA fees, and other housing costs are not included.
The full principal-and-interest payment at 7.00% would be approximately:
$2,661 per month
1-0 Buydown Example
With a 1-0 buydown:
Period | Payment Rate Used | Approx. Monthly P&I | Approx. Monthly Subsidy |
Year 1 | 6.00% | $2,398 | $263 |
Year 2+ | 7.00% | $2,661 | $0 |
The estimated Year 1 subsidy would be:
$263 × 12 = approximately $3,156
So, in this hypothetical example:
Estimated 1-0 buydown cost: $3,156
2-1 Buydown Example
With a 2-1 buydown on the same loan:
Period | Payment Rate Used | Approx. Monthly P&I | Approx. Monthly Subsidy |
Year 1 | 5.00% | $2,147 | $514 |
Year 2 | 6.00% | $2,398 | $263 |
Year 3+ | 7.00% | $2,661 | $0 |
The estimated subsidy would be:
Year 1: approximately $6,167
Year 2: approximately $3,156
Estimated total 2-1 buydown cost: $9,323
In this example, the 2-1 buydown provides significantly more temporary payment relief, but it also requires approximately $6,167 more funding than the 1-0 structure.
Actual payment amounts and temporary buydown costs depend on the specific mortgage terms.
Which Costs More, a 1-0 or 2-1 Buydown?
A 2-1 buydown generally costs more than a 1-0 buydown because it provides both a larger first-year payment reduction and an additional year of payment assistance.
The cost of a 1-0 buydown can be expressed as:
(Full Payment - Year 1 Payment) × 12
A 2-1 buydown requires funding for two separate payment differences:
[(Full Payment - Year 1 Payment) × 12] + [(Full Payment - Year 2 Payment) × 12]
The additional cost of a 2-1 buydown is not simply the Year 2 subsidy.
Its Year 1 payment reduction is also larger.
In our $400,000 example:
1-0 estimated cost: $3,156
2-1 estimated cost: $9,323
Difference: approximately $6,167
That additional funding buys the borrower a greater first-year reduction plus another year of temporary payment relief.
Which Buydown Has the Lower First-Year Payment?
A 2-1 buydown generally provides the lower first-year payment.
Using a 7.00% note rate:
1-0 buydown Year 1: payment based on 6.00%
2-1 buydown Year 1: payment based on 5.00%
In the $400,000 example:
1-0 Year 1 payment: approximately $2,398
2-1 Year 1 payment: approximately $2,147
That is a difference of approximately $251 per month during the first year.
The lower payment can be valuable to a buyer, but it also increases the amount required to fund the temporary subsidy.
When Does the Full Mortgage Payment Begin?
The timing is another important difference.
Buydown Type | Full Scheduled Payment Begins |
1-0 Buydown | Year 2 |
2-1 Buydown | Year 3 |
With either structure, the transition to the full payment should not come as a surprise.
The mortgage note rate is established at the beginning of the loan. The temporary buydown simply reduces the amount the borrower pays during the subsidy period.
A buyer should therefore evaluate affordability using the full scheduled mortgage payment, not just the lower introductory payment.
Borrowers who want to understand how monthly obligations affect mortgage qualification can also review our guide to debt-to-income ratios for mortgages.
Who Can Pay for a 1-0 or 2-1 Buydown?
Depending on the mortgage program and transaction, temporary buydown funds may potentially come from eligible sources such as:
A seller
A home builder
A lender
Another permitted source
The permitted funding source and contribution amount depend on the specific mortgage program and transaction.
Because a 1-0 buydown only provides one year of assistance, it generally requires less funding than a 2-1 structure.
That can make it easier to fit within a smaller available seller or builder contribution.
For more information about seller contributions, read Seller Concessions in New Hampshire.
Seller-Paid 1-0 vs. Seller-Paid 2-1 Buydown
The amount of seller funding available can play an important role in determining which temporary buydown structure is practical.
Seller-Paid 1-0 | Seller-Paid 2-1 | |
Temporary relief | 1 year | 2 years |
First-year payment reduction | Smaller | Greater |
Seller funds required | Generally lower | Generally higher |
Full payment begins | Year 2 | Year 3 |
May fit smaller concession | More likely | Less likely |
Suppose a seller is willing and permitted to provide $4,000 toward a temporary buydown.
A 1-0 structure might fit within that amount in a given mortgage scenario, while a full 2-1 buydown might require substantially more funding.
If a larger eligible contribution is available, the buyer may have more flexibility to consider the 2-1 option.
In either case, seller contributions must meet the applicable mortgage program and transaction requirements.
1-0 vs. 2-1 Buydown: Which Is Better?
Neither option is universally better.
A 1-0 buydown may be more attractive when the buyer wants temporary payment relief without requiring a large subsidy.
A 2-1 buydown may be more attractive when the buyer places greater value on lower initial payments and an additional year of assistance.
A 1-0 Buydown May Make More Sense If
A 1-0 structure may be worth considering when:
The available seller or builder contribution is relatively limited.
One year of temporary payment relief is sufficient.
The buyer wants to minimize the amount required to fund the buydown.
The full scheduled payment beginning in Year 2 is affordable.
Available funds are also needed for other transaction expenses.
A 2-1 Buydown May Make More Sense If
A 2-1 structure may deserve consideration when:
A larger eligible contribution is available.
Lower first-year payments are especially valuable.
The buyer would benefit from a second year of temporary relief.
The full scheduled payment beginning in Year 3 is affordable.
The additional subsidy cost makes sense relative to other uses of the funds.
The decision should be based on the actual mortgage numbers and available funding rather than simply choosing the option with the lowest first-year payment.
Is the Second Year of a 2-1 Buydown Worth the Extra Cost?
This is one of the most useful questions when comparing the two structures.
A 1-0 buydown gives the buyer one year of payment relief.
A 2-1 buydown adds two benefits:
A deeper reduction in Year 1
An additional subsidy during Year 2
The buyer should therefore ask whether those additional savings justify the higher funding requirement.
If an eligible seller is already offering enough funds to cover a 2-1 buydown, the additional temporary relief may be attractive.
If the buyer would need to give up closing-cost assistance or another valuable use of seller funds to obtain the 2-1 structure, a 1-0 buydown may deserve closer consideration.
1-0 or 2-1 Buydown vs. a Permanent Rate Buydown
Temporary and permanent buydowns work differently.
1-0 or 2-1 Temporary Buydown | Permanent Rate Buydown | |
Main benefit | Lower initial payments | Lower long-term interest rate |
Does note rate change? | No | Yes |
Benefit period | 1 or 2 years | Potentially life of loan |
Funding | Temporary payment subsidy | Discount points or lender pricing |
Main consideration | Short-term payment relief | Long-term savings and break-even |
With a permanent rate buydown, mortgage discount points are generally paid upfront in exchange for a lower interest rate.
One point generally equals 1% of the loan amount, but the rate reduction available for that point is not fixed.
For more information, read Mortgage Points and Buying Down Your Rate.
1-0 or 2-1 Buydown vs. a Seller Price Reduction
A seller who is willing to provide financial assistance may have several ways to structure that value.
Strategy | Main Buyer Benefit |
Price reduction | Lower purchase price |
Closing-cost assistance | Less cash needed at closing |
1-0 buydown | Lower mortgage payment for 1 year |
2-1 buydown | Greater payment relief for 2 years |
These options are not interchangeable.
A price reduction lowers the amount paid for the property.
A closing-cost credit can reduce the buyer’s upfront cash requirement.
A 1-0 buydown concentrates a smaller amount of assistance into the first year.
A 2-1 buydown provides a larger benefit across two years but requires more funding.
The best use of a seller contribution depends on the buyer’s priorities, loan structure, available cash, and long-term plans.
What Should Buyers Consider Before Choosing?
Temporary payment relief can be useful, but buyers should look beyond the introductory payment.
Can You Afford the Full Scheduled Payment?
This is the most important consideration.
With a 1-0 buydown, the full payment generally begins in Year 2.
With a 2-1 buydown, it generally begins in Year 3.
A buyer should be comfortable making that payment even if their financial circumstances do not improve.
How Much Contribution Is Available?
A smaller seller or builder contribution may support a 1-0 buydown but may not be enough to fund a full 2-1 structure.
The available funding can therefore influence the practical choice.
Could the Funds Be More Valuable Elsewhere?
Eligible funds might potentially be used toward other transaction expenses.
Depending on the loan and transaction, buyers may want to compare:
Closing-cost assistance
Temporary buydown funding
Mortgage discount points
Other permitted costs
The option with the biggest first-year payment reduction is not necessarily the option that creates the most overall value.
How Valuable Is the Second Year of Assistance?
This is the central difference between the two options.
If the buyer would benefit significantly from an additional year of lower payments, the higher cost of a 2-1 structure may be worth comparing.
If one year of relief is enough, a 1-0 may provide a more economical temporary solution.
Are You Assuming You Will Refinance?
A buyer should not choose a temporary buydown solely because they expect to refinance before the full payment begins.
Future mortgage rates cannot be predicted with certainty.
Future refinancing can also depend on income, credit, property value, equity, debt obligations, closing costs, and lending requirements.
For more context, read When to Refinance a Mortgage in New Hampshire.
Can You Use a 1-0 or 2-1 Buydown With Different Loan Programs?
Temporary buydown requirements vary by mortgage program.
Conventional Loans
Temporary buydowns used with conventional loans must meet the applicable conventional financing requirements, including rules around funding sources and interested-party contributions.
FHA Loans
FHA loans have their own requirements for temporary buydowns and interested-party contributions.
The proposed structure must meet applicable FHA and lender guidelines.
VA Loans
VA loans also have program-specific requirements regarding seller contributions, concessions, and temporary buydowns.
Because funding rules, contribution limits, qualification standards, and temporary buydown requirements can vary, buyers should confirm the structure for their specific mortgage before relying on it as part of the transaction.
How to Compare a 1-0 and 2-1 Buydown
The best way to compare these options is to use the same mortgage assumptions for both.
Step 1: Calculate the Full Mortgage Payment
Start with the actual loan amount, loan term, and note rate.
Step 2: Calculate the 1-0 Payment
Determine the Year 1 payment using a rate 1 percentage point below the note rate.
Then calculate the total Year 1 subsidy.
Step 3: Calculate the 2-1 Payments
Determine:
Year 1 payment at 2 percentage points below the note rate
and
Year 2 payment at 1 percentage point below the note rate
Then calculate the total two-year subsidy.
Step 4: Compare Total Funding Requirements
Look beyond the monthly payment.
Compare the full amount required to fund each option.
Step 5: Review Available Seller or Builder Funds
Determine whether the available eligible contribution can support one or both structures.
Step 6: Compare Alternative Uses of the Funds
Consider whether available funds might provide more value when used for closing costs, mortgage points, or another permitted expense.
Step 7: Review the Full Scheduled Payment
Finally, make sure the regular mortgage payment remains affordable once the temporary subsidy ends.
Talk to a NextGen Mortgage Professional
Frequently Asked Questions About 1-0 vs. 2-1 Buydowns
What is the difference between a 1-0 and 2-1 buydown?
A 1-0 buydown temporarily reduces the borrower’s payment for one year. A 2-1 buydown provides reduced payments for two years and generally offers a larger payment reduction during the first year.
Which costs more, a 1-0 or 2-1 buydown?
A 2-1 buydown generally costs more because it provides a larger Year 1 subsidy and an additional year of payment assistance.
Which buydown has the lower first-year payment?
A 2-1 buydown generally produces the lower Year 1 payment because the payment is calculated 2 percentage points below the note rate rather than 1 percentage point below it.
When does the full payment begin with a 1-0 buydown?
The full scheduled mortgage payment generally begins in Year 2.
When does the full payment begin with a 2-1 buydown?
The full scheduled payment generally begins in Year 3.
Does a 1-0 buydown permanently reduce the mortgage rate?
No. A 1-0 buydown temporarily subsidizes the borrower’s first-year payment. It does not permanently change the mortgage note rate.
Can a seller pay for a 1-0 buydown?
Potentially. A seller may be able to provide eligible funds toward a 1-0 temporary buydown when permitted by the applicable mortgage program and transaction requirements.
Is a 1-0 buydown better than a 2-1 buydown?
Not necessarily. A 1-0 usually requires less funding, while a 2-1 provides greater and longer temporary payment relief. The better option depends on the buyer’s priorities and available contribution.
Is a 1-0 buydown cheaper than buying mortgage points?
The strategies serve different purposes. A 1-0 buydown provides temporary payment relief for one year, while mortgage points are generally used to obtain a permanently lower interest rate. Buyers should compare both the upfront cost and duration of the benefit.
Compare 1-0 and 2-1 Buydown Options
A 1-0 and 2-1 buydown can both reduce a homebuyer’s initial mortgage payments, but they offer different levels of assistance.
A 1-0 buydown provides one year of payment relief and generally requires less funding.
A 2-1 buydown provides a larger first-year reduction plus a second year of assistance, but generally requires a significantly larger subsidy.
The best option depends on the mortgage amount, note rate, available seller or builder contribution, full future payment, and how valuable the additional temporary savings are to the buyer.
Compare both structures using the same loan assumptions before deciding which one fits the transaction.
Talk to a NextGen Mortgage Professional
Examples in this article are for educational purposes only and are not an offer or commitment to lend. Actual mortgage rates, payments, temporary buydown costs, permitted funding sources, contribution limits, and eligibility requirements vary by loan program and transaction.

