Conventional Loans
Conventional financing, including high-balance options permitted under the Middlesex County limit of $962,550.
Conventional loans →
Home › Massachusetts › Chelmsford Mortgage Broker
Buying, refinancing or investing in Chelmsford? We are a Massachusetts-licensed mortgage broker with a local office at 2 Omni Way, comparing loan programs across multiple wholesale lenders.
Chelmsford and Middlesex County, as of September 2026
NextGen Mortgage is a mortgage broker serving Chelmsford, MA and Middlesex County from an office at 2 Omni Way, Office #2, Chelmsford, MA 01824. Unlike a bank that offers only its own mortgage products, a broker can compare programs and pricing across multiple wholesale lenders.
We work with first-time buyers, move-up families, veterans, self-employed borrowers and investors across Chelmsford, Lowell, Westford, Billerica and the surrounding Merrimack Valley towns.
NextGen Mortgage is a mortgage broker, not a direct lender.
We arrange financing rather than funding loans ourselves. That means we shop your file across our lender network instead of fitting you into one institution's guidelines.
Sit down with a loan officer in person, or start by phone. Both work.

A bank can only offer what a bank has. A broker shops your file.
| Bank or direct lender | NextGen Mortgage broker |
|---|---|
| One lender's programs | Multiple wholesale lenders |
| One underwriting framework | Ability to compare lender guidelines |
| Apply separately to each to compare | One broker relationship |
| Standard borrower focus | Conventional plus specialty options |
| Bank-employed loan officer | A broker working to place your loan |
NextGen Mortgage arranges financing and does not fund loans. Program availability, pricing and approval depend on lender guidelines and individual qualifications.
Four numbers that shape what your Chelmsford pre-approval needs to cover.
| Measure | Figure | Source |
|---|---|---|
| Median sale price | ~$647,926 | Redfin, three months ending July 2026 — Chelmsford housing market |
| Median days on market | 19 days | Redfin, three months ending July 2026 |
| 2026 conforming loan limit, one unit | $962,550 | FHFA, Middlesex County |
| FY2026 property tax rate | $13.60 | Per $1,000 of assessed value — Town of Chelmsford tax classification hearing |
Chelmsford sits in the higher-cost Boston-area market but prices below neighboring Westford and much of Middlesex County. With a median around the mid-$600Ks and homes moving in roughly three weeks, most buyers here need a written pre-approval before they start touring.
Chelmsford is in Middlesex County, which federal agencies treat as a higher-cost market.
| Property type | 2026 conforming limit |
|---|---|
| 1 unit | $962,550 |
| 2 units | $1,232,250 |
| 3 units | $1,489,500 |
| 4 units | $1,851,100 |
HUD's 2026 data sets the Middlesex County one-unit FHA limit at $962,550, with higher limits on two- to four-unit properties.
Because Chelmsford is part of the Boston-area high-cost market, buyers can finance considerably more under conforming and FHA limits than borrowers in many lower-cost counties. With Chelmsford home prices around the mid-$600Ks, most homes here stay within conforming and FHA limits rather than automatically requiring jumbo financing.
Sources: FHFA 2026 conforming loan limits · HUD FY2026 loan limits
Start here, then talk to a loan officer about which one your file actually fits.
Conventional financing, including high-balance options permitted under the Middlesex County limit of $962,550.
Conventional loans →Lower-down-payment financing with more flexible credit guidelines. The 2026 Middlesex County FHA limit is $962,550.
FHA loans →Zero-down financing for eligible veterans, service members and qualifying surviving spouses.
VA loans →For loan amounts above the applicable conforming limit, which in Chelmsford means financing beyond $962,550 on a single-family home.
Purchase financing →FHA, low-down-payment conventional programs, and eligible MassHousing options available through select participating lenders.
First-time buyer options →Rate-and-term refinancing to change your payment or term, and cash-out refinancing to access equity.
Refinance loans →Financing for rental and investment properties, qualified on property cash flow rather than personal income.
DSCR loans →A 15-minute call covers your credit, income, down payment and timeline. We will tell you which programs are realistic before you tour a single house.
Talk to a loan officer →Compare low-down-payment mortgage programs and eligible Massachusetts housing options.
Buying your first home in Chelmsford does not always require a large down payment. Depending on your income, credit, property type and overall loan profile, you may qualify for FHA financing, low-down-payment conventional financing, or certain MassHousing options.
NextGen Mortgage can compare first-time buyer programs available through our lender network. MassHousing mortgage and down payment assistance options may be available through select participating lenders, so availability can vary based on the lender, borrower eligibility, property requirements, income limits and current program guidelines.
We will review your credit, income, available down payment, estimated purchase price and monthly budget to identify the financing options currently available to you before you make an offer on a Chelmsford home.
Program availability is not guaranteed. MassHousing products are subject to MassHousing requirements and participating-lender availability. FHA and conventional loans are subject to lender underwriting, credit approval and applicable program guidelines.
| Option | What to know |
|---|---|
| FHA loans | 3.5% downMinimum down payment for qualifying borrowers; mortgage insurance applies |
| Low-down-payment conventional | As low as 3%Available on certain conventional programs for qualifying borrowers |
| MassHousing options | Eligibility variesMortgage and assistance options may be available through select participating lenders |
Your monthly payment is more than principal and interest. Here is everything that lands in it.
This is an illustration, not a quote. It excludes exemptions, abatements and future assessment changes, and does not reflect your loan terms. For a real payment estimate, request a pre-approval.
Our Chelmsford office serves buyers and homeowners across Middlesex County and the towns along the New Hampshire border.
Chelmsford sits minutes from the New Hampshire line, and plenty of our clients are comparing homes on both sides of it. We are licensed in Massachusetts and New Hampshire, so a buyer weighing Chelmsford against Nashua does not need two brokers.
Nearby: Nashua, NH · Manchester, NH · All of Massachusetts
Chelmsford had an estimated 38,549 residents in 2025, and roughly 82.1% of housing units were owner-occupied in the 2020–2024 estimates — an unusually high ownership rate that shapes both inventory and how quickly listings move.
Source: U.S. Census Bureau QuickFacts
Five steps from the first phone call to the closing table.
We go through property type, income, credit and what you are trying to do. No credit pull is needed for the first conversation.
We review the programs available through our lender network and show you which ones your file qualifies for and what each costs you monthly.
You receive a written pre-approval before making an offer. In a market where Chelmsford homes move in about 19 days, this is what makes your offer credible.
Once you are under contract, the lender verifies your financials and orders an appraisal on the property. We handle the back-and-forth.
You sign, the loan funds, and you get the keys. We stay on the file through closing day rather than handing you to a processing queue.
One licensed professional, from the first call through closing day.
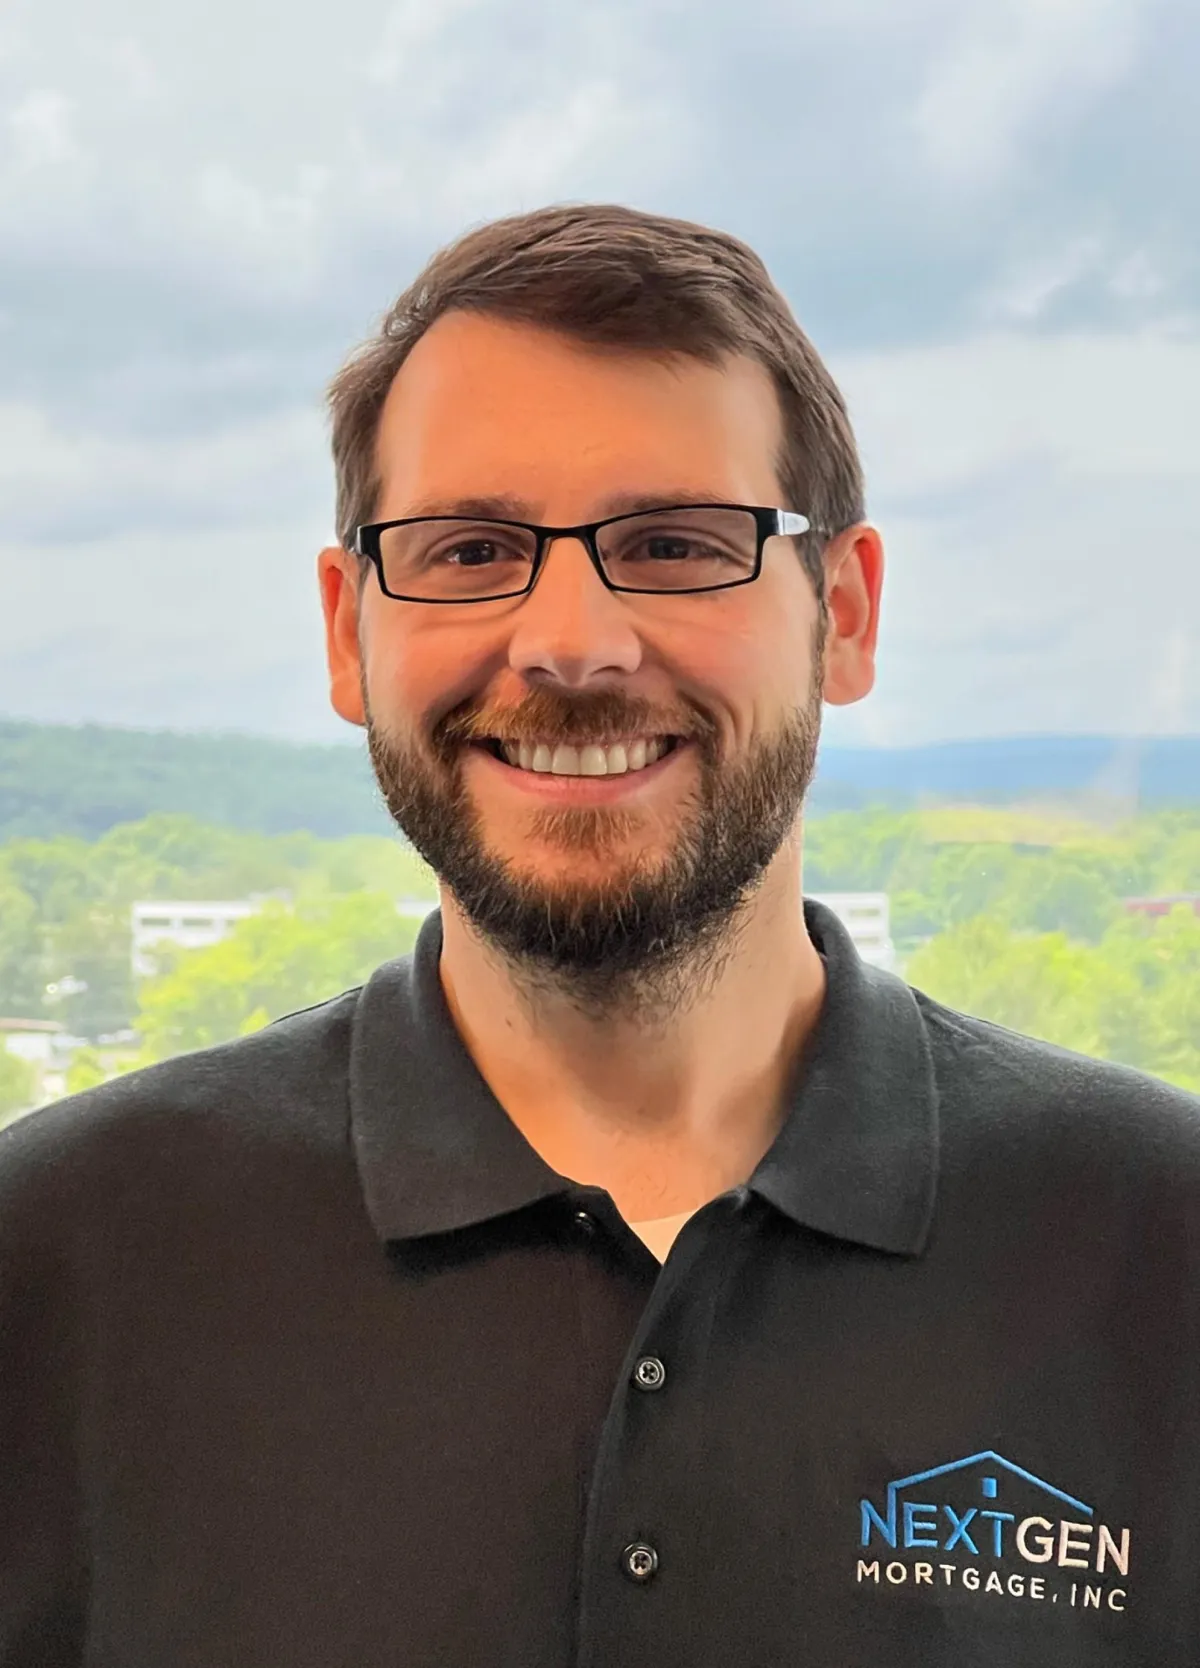
Mike founded NextGen Mortgage in 2017, after starting his career at his family's brokerage. He leads a team that works with more than 30 banks and wholesale lenders, which is what lets a Chelmsford file get shopped rather than squeezed into one set of guidelines. Call him directly or email him — you will not be routed through a queue.
Short answers first. Ask us anything that is not here.
Yes. NextGen Mortgage has an office at 2 Omni Way, Office #2, Chelmsford, MA 01824.
The branch is reachable at (877) 411-0123 and is open Monday through Friday, 9:00am to 6:00pm, and Saturday 9:00am to 2:00pm. You can meet a loan officer in person or start the process by phone.
The 2026 conforming loan limit for a one-unit property in Middlesex County, including Chelmsford, is $962,550.
Multi-unit limits are higher: $1,232,250 for two units, $1,489,500 for three units and $1,851,100 for four units. Loan amounts above the applicable limit are financed as jumbo loans.
HUD's 2026 FHA limit for a one-unit property in Middlesex County is $962,550.
Because Chelmsford's median sale price sits around the mid-$600Ks, the great majority of single-family homes in town fall within that FHA limit rather than requiring jumbo financing.
It depends on the program: VA loans allow 0% down for eligible borrowers, FHA starts at 3.5%, and conventional programs start around 3% to 5%.
On a $650,000 Chelmsford home, 3.5% is roughly $22,750 and 5% is $32,500. Massachusetts down payment assistance may reduce what you bring to closing if you qualify. Your credit profile, debt-to-income ratio and property type all affect the minimum.
Yes. That is the core difference between a broker and a bank.
A bank can only offer its own products and its own underwriting guidelines. As a broker, NextGen submits your file across a network of wholesale lenders and compares programs and pricing, so you are not applying separately to five institutions to find out who fits.
Yes. Eligible Chelmsford buyers may have access to FHA loans, low-down-payment conventional programs, and certain MassHousing options.
FHA financing may allow qualified borrowers to purchase with as little as 3.5% down, while certain conventional programs may allow as little as 3% down. MassHousing mortgage and down payment assistance options may also be available through select participating lenders. Availability depends on borrower eligibility, income and purchase-price limits, property requirements, lender participation and current program guidelines. NextGen Mortgage can compare the options available through our lender network for your specific situation.
Yes, and you should.
Chelmsford homes have been selling in roughly 19 days. A written pre-approval tells you your real budget, tells your agent which listings to show you, and makes your offer competitive against buyers who already have one.
Yes. Self-employed borrowers can qualify through conventional and FHA programs, and through alternative documentation programs such as bank statement loans.
Standard programs generally look at two years of tax returns. Bank statement programs qualify income from 12 or 24 months of deposits instead, which often works better for business owners with significant write-offs. See bank statement loans.
Yes. NextGen arranges both rate-and-term and cash-out refinances for Chelmsford homeowners.
A rate-and-term refinance changes your rate or loan term. A cash-out refinance converts equity into funds for renovations, debt consolidation or other goals. Whether either makes sense depends on your current rate, remaining balance and how long you plan to stay. See refinance options.
Yes, including DSCR loans that qualify on the property's rental income rather than your personal income.
Middlesex County's multi-unit conforming limits — $1,232,250 for two units and $1,489,500 for three — also make small multifamily purchases in and around Chelmsford financeable without jumbo terms in many cases. See DSCR loans.
Sourced figures for Chelmsford, Middlesex County, Massachusetts.
Last reviewed: September 2026
Reviewed by: Mike Gill Jr., NMLS #1621958
A written pre-approval tells you what you can actually afford, strengthens your offer, and saves weeks once you find the right house. Start it today, in person at 2 Omni Way or over the phone.
Chelmsford office · Licensed in Massachusetts · Multiple wholesale lenders · Purchase & refinance
NextGen Mortgage, Inc. is a mortgage broker. We arrange loans with third-party wholesale lenders and do not make loans or commitments to lend. All loans are subject to credit approval, property appraisal and lender guidelines. Rates, programs and terms are subject to change without notice. Figures shown on this page are illustrations, not quotes or offers of credit. Equal Housing Opportunity.
MLO License Info: NMLS #1621958, NH Broker license #1621958MBRR, and MA Broker license #MB1621958, ME Broker License #1621958, FL Broker License #MBR4542, RI Broker License #20265029LB
