DSCR Loans For
Real Estate Investors
Investment property financing without traditional personal-income qualification, including DSCR and select no-ratio options.

From 620 FICO
From 15% down
LLC & short-term rentals
Comparing programs across our lending partner network
30+
Lending partners
620+
FICO program options
15%+
Down payment options
80%
Max LTV for Cash-Out
Does This Sound Like Your Situation?
What Is a DSCR Loan (Debt-Service Coverage Ratio loan)?
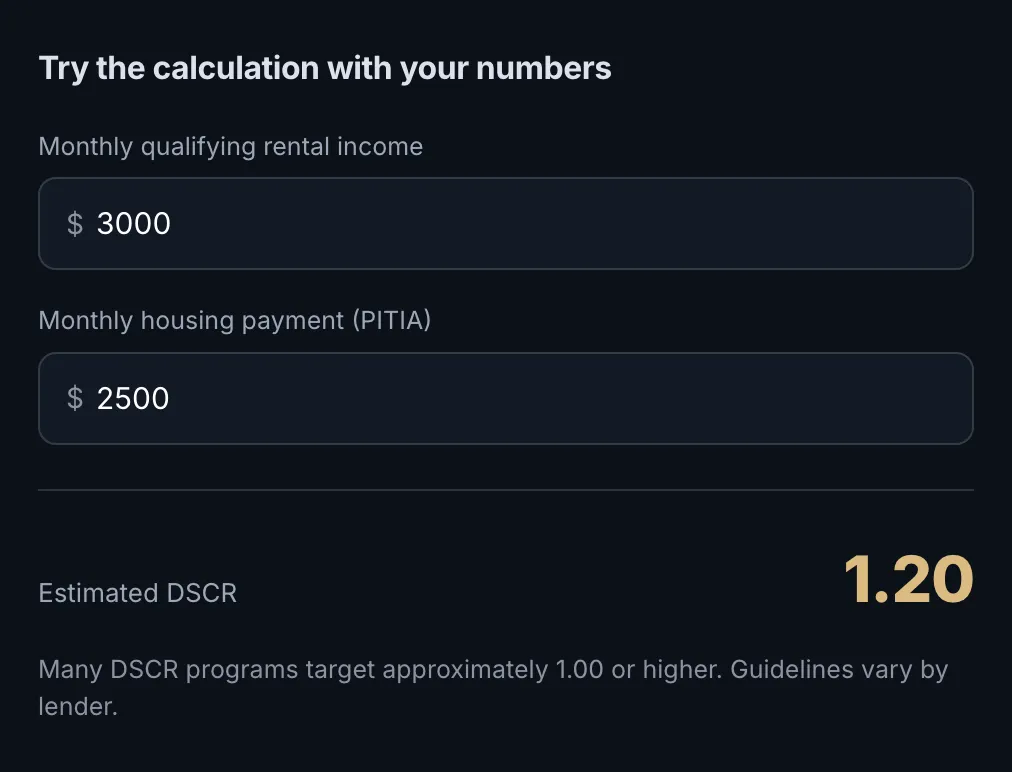
A DSCR loan is an investment property financing option built around the property’s rental income rather than the borrower’s personal income. Instead of reviewing W-2s, tax returns or employment history, lenders look at how the monthly rent compares to the monthly housing payment.
If the rental income covers that payment, the property can often qualify on its own, even when a borrower’s personal financial profile wouldn’t fit a traditional mortgage. And when a property does not meet a traditional DSCR threshold, select no-ratio or lower-DSCR programs may still provide a financing path.
NextGen Mortgage is a mortgage broker,
not a direct lender.
We evaluate your investment scenario and compare available DSCR programs from our lending partners.
How a DSCR Loan Works
From first conversation to closing, here’s how we help you find a program that fits your investment.

Tell us about the property
Share the property you’re purchasing or refinancing, along with its expected monthly rental income.

We compare lending partners
Your scenario is checked against DSCR programs across our network of 30+ lending partners.

Review your matched options
See the programs you may qualify for, side by side: rate, LTV, DSCR requirement and terms.

Lock your program & close
Move forward with the lending partner and program that best fits your investment goals.
Why Choose NextGen Mortgage Broker
Direct lender / traditional bank
- Limited portfolio loan products
- One institution’s guidelines
- Stricter underwriting
- Less flexibility for unique investor situations
- Fewer alternatives if the scenario doesn’t fit
NextGen as a mortgage broker
- Access to 30+ lending partners
- Multiple DSCR programs and guidelines
- More flexibility for investor scenarios
- Ability to compare financing structures
- More potential solutions for unique circumstances
Client Testimonials
Don't just take our word for it. Hear from the families we've helped
secure their dream homes.
The person guiding your DSCR financing
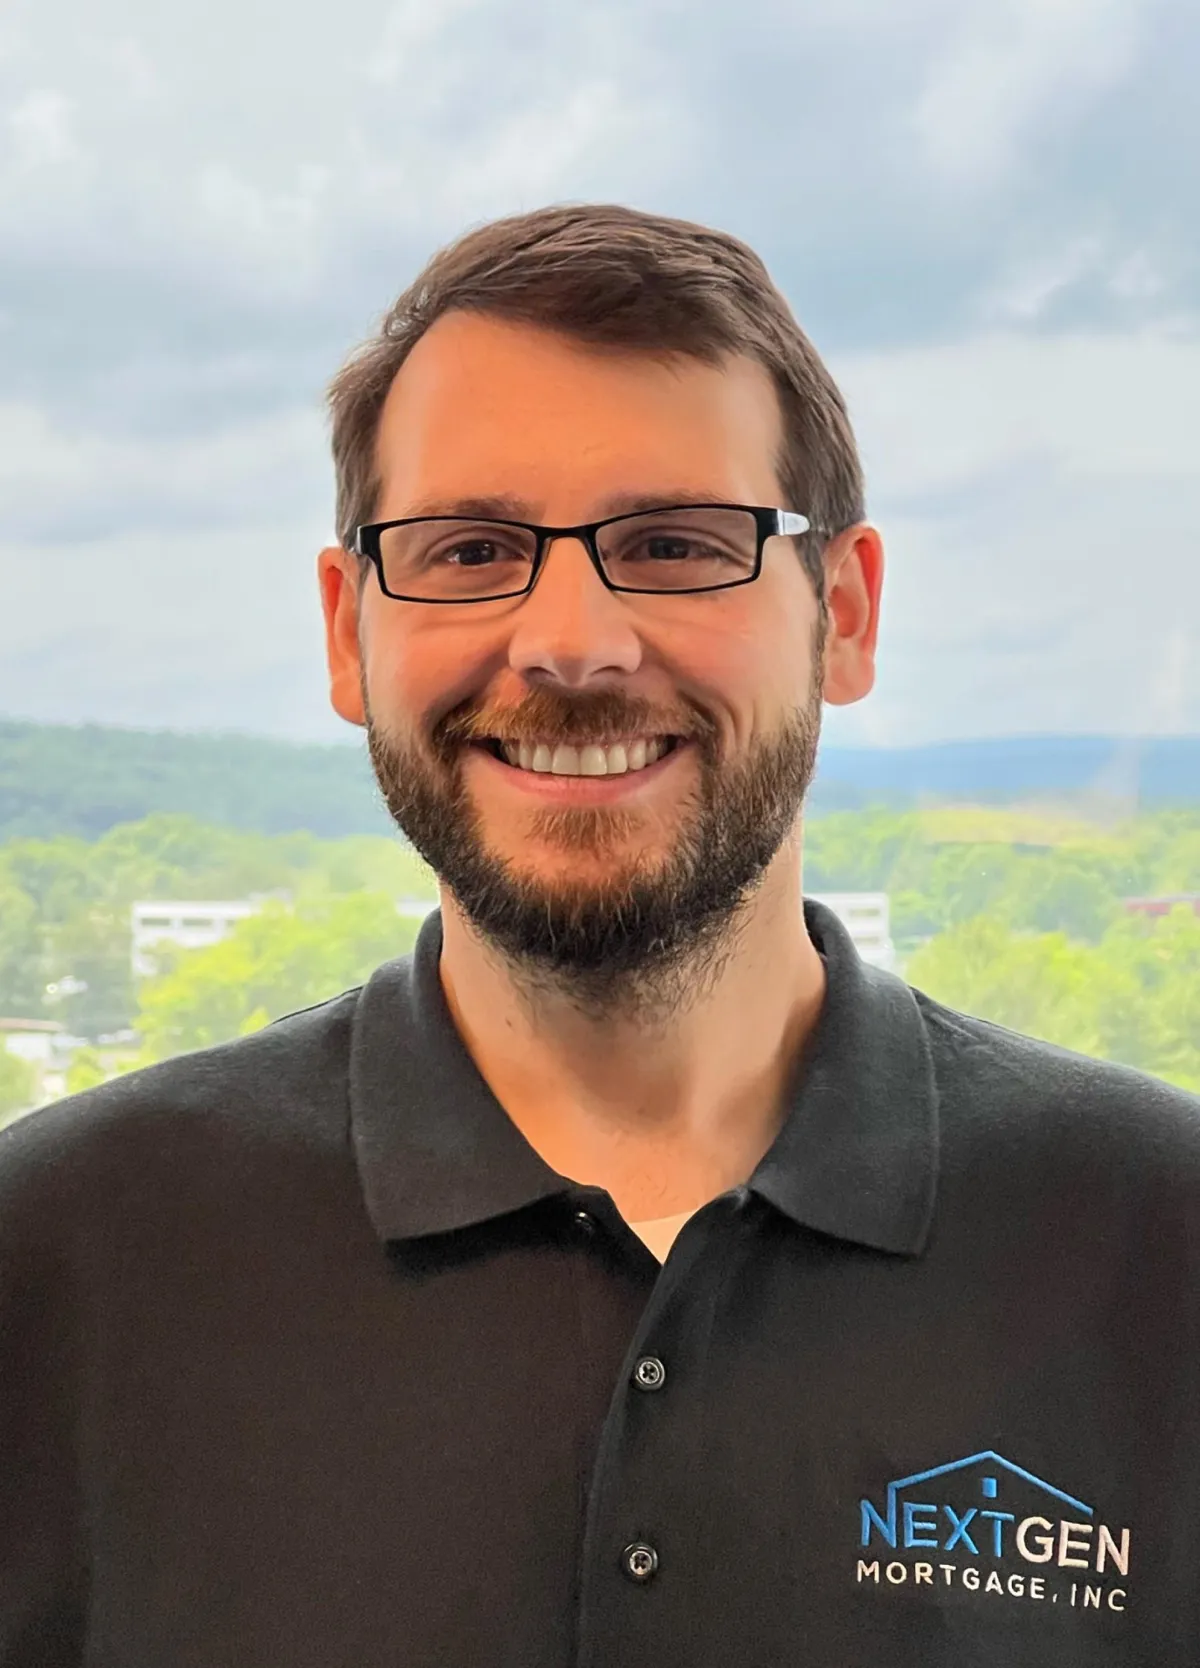
Mike Gill Jr.
Founded NextGen Mortgage in 2017 after starting his career at his family’s brokerage. Leads a team that partners with 30+ banks and lenders to secure financing options for investors.
Who May Be a Good Fit for DSCR Financing?
DSCR financing can work for a wide range of real estate investors because qualification focuses primarily on the investment property and its income potential rather than traditional personal-income documentation.
Real Estate Investors
Investors purchasing, refinancing or accessing equity from residential investment properties.
Self-Employed Investors
Borrowers whose tax returns or reported personal income may not accurately reflect their financial position.
Experienced Portfolio Investors
Investors who already own multiple rental properties and want financing designed around investment-property cash flow.
ITIN & Non-Traditional Income Borrowers
Select programs may be available for borrowers who do not fit conventional mortgage qualification structures.
Long-Term Residential Rental Properties
Investors purchasing or refinancing residential properties intended for traditional long-term tenants.
Airbnb & Short-Term Rental Properties
Eligible Airbnb, VRBO and other short-term rental properties may qualify under specialized DSCR programs.
Vacation Rental Properties
Financing options may be available for eligible vacation and seasonal rental investment properties.
LLC or Business Entity Buyers
Many programs allow eligible investment properties to close in an LLC or other approved business entity.
DSCR Financing Options at a Glance
Credit score
Programs available starting around 620 FICO
Down payment
Options starting around 15% down
LTV
Up to 80% LTV for Cash-Out Refinance
No-Ratio DSCR Options
Financing May Be Available Even When the Property Does Not Meet a Traditional DSCR Threshold
Personal Income Verification
No Traditional Personal Income Qualification With Many Programs
Tax Returns
Personal or Business Tax Returns May Not Be Required
Down Payment & Gift Funds
Select Programs May Allow Gift Funds With Reduced or No Sourcing Requirements
Fixed-Rate DSCR Second Mortgages
Access Equity Without Replacing Your Existing First Mortgage
Interest-Only Options
Interest-Only Structures May Be Available
Guidelines, pricing and terms vary by lending partner and borrower scenario. Figures reflect illustrative program ranges and are
not a guarantee of qualification.
What if the property doesn't meet the typical DSCR requirement?
No-ratio and lower-DSCR programs may still be available.
A property does not necessarily need to meet a traditional 1.00 or 1.25 DSCR threshold to qualify for investment property financing.
Through our lending partner network, NextGen Mortgage can evaluate select no-ratio and lower-DSCR programs for scenarios where the property's rental income does not meet standard DSCR requirements.
This can be especially useful for investors purchasing properties with below-market rents, properties transitioning to new rental strategies, or deals where the traditional DSCR calculation doesn't tell the full story.
Availability depends on credit profile, property type,
leverage, loan purpose and lending partner guidelines.
Example property DSCR
0.85
Lower DSCR scenarios
Options may exist even when the property falls below traditional DSCR thresholds.
No-ratio programs
Select lending partners may offer programs without a standard minimum DSCR requirement.
30+ lending partners
We compare available programs instead of relying on one lender's guidelines.
Your investment property
How the loans stack up
-
Keep
1st mortgage
Stays in place at your current rate
-
New
Fixed-rate DSCR 2nd
Access available equity
-
Remaining equity
Stays with you
Access equity without giving up your existing mortgage rate
Fixed-rate DSCR second mortgage options.
Already have a strong interest rate on your investment property's first mortgage? Refinancing the entire balance just to access equity may not always make sense.
Select fixed-rate DSCR second mortgage programs may allow qualifying investors to access available property equity while keeping their existing first mortgage in place.
This may be useful for investors looking to:
- Fund another investment property purchase
- Renovate or improve existing rental properties
- Access capital for portfolio expansion
- Consolidate eligible obligations
- Preserve an attractive existing first-mortgage rate
Program availability, maximum LTV, loan amounts and qualification requirements vary by lending partner.
Cash-out refinance vs. DSCR second mortgage
What Determines Your DSCR Loan Options?
Credit score
What your FICO opens up
Programs may be available starting around 620 FICO, while stronger credit may provide access to better pricing or additional options.
Down payment
How much you put in
For purchases, select programs may offer financing up to approximately 80% LTV, or as little as 15% down, while a larger down payment can improve the available financing structure.
Cash flow
What the property earns
For traditional DSCR programs, stronger property cash flow can improve the range of available options. Select no-ratio programs may also be available when the property does not meet a standard DSCR threshold.
Frequently Asked Question
Can you get a DSCR loan below 1.0?
Potentially. While many DSCR programs target a ratio around 1.00 or above, some lending partners offer programs for lower-DSCR or no-ratio investment scenarios. Eligibility, leverage, pricing and other requirements can differ significantly between programs.
Can you close a DSCR loan in an LLC?
Many DSCR lending programs allow eligible investment properties to close in an LLC or other permitted business entity. Requirements vary by lender, entity structure and borrower scenario, so NextGen compares the available guidelines before recommending a financing path.
Can you use a DSCR loan for Airbnb?
Yes, some DSCR lending programs allow eligible Airbnb, VRBO and other short-term rental properties. How rental income is calculated and which documentation is accepted varies between lending partners.
Are interest-only DSCR loans available?
Some lending partners offer interest-only payment structures for eligible DSCR borrowers. These structures may improve near-term property cash flow, although qualification, pricing and repayment terms vary by program.
What about a DSCR cash-out refinance?
Eligible investors may use a DSCR cash-out refinance to access equity in an investment property for renovations, portfolio expansion or other eligible purposes. NextGen compares available cash-out programs based on property value, DSCR, credit and lender guidelines.
Are there programs for foreign national investors?
NextGen can evaluate foreign-national investor scenarios against specialty programs available through participating lending partners. Documentation and qualification requirements vary by lender.
Let’s compare DSCR loan options for your investment.
Share a few details about your scenario and we’ll help identify which lending partner programs may fit.
MLO License Info: NMLS #1621958, NH Broker license #1621958MBRR, and MA Broker license #MB1621958, ME Broker License #1621958, FL Broker License #MBR4542, RI Broker License #20265029LB
Company
Services
Contact
MLO License Info: NMLS #1621958, NH Broker license #1621958MBRR, and MA Broker license #MB1621958, ME Broker License #1621958, FL Broker License #MBR4542, RI Broker License #20265029LB
Company
Services
Contact
